Filing a Roof Damage Insurance Claim in Southwest Florida: A Step-by-Step Guide
Filing a Roof Damage Insurance Claim in Southwest Florida: A Step-by-Step Guide
Understanding Roof Damage in Southwest Florida
Southwest Florida is no stranger to extreme weather conditions that can wreak havoc on roofs. Hurricanes, tropical storms, hail, and high winds are frequent culprits of roof damage in this region. These weather events bring heavy rainfall, flying debris, and wind gusts strong enough to tear shingles off or even collapse sections of a roof. Homeowners in this area need to be vigilant because the unique climate and geography make their properties particularly vulnerable to such risks.
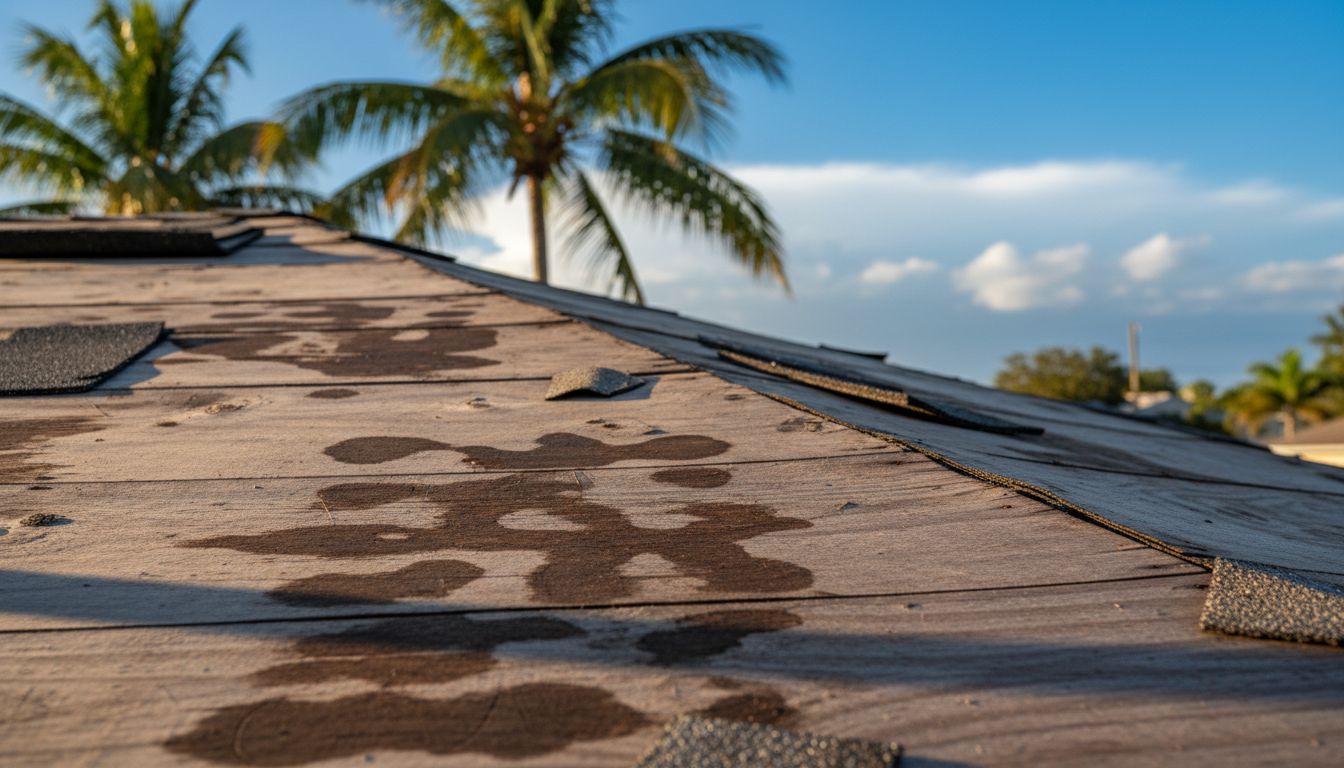
Because of these threats, it’s crucial for homeowners to regularly inspect their roofs for signs of damage, especially after major storms. Look for missing shingles, dents from hail, leaks, or sagging areas that could indicate structural issues. Being proactive can save you from costly repairs down the line and ensure your home remains safe and secure.
Evaluating and Documenting Roof Damage
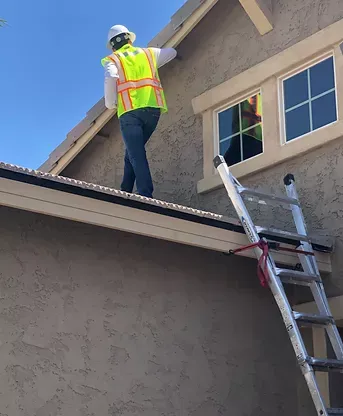
If you suspect your roof has been damaged, the first step is to assess the situation. For minor inspections, you might be able to spot visible issues like missing shingles or water stains from the ground or using a ladder safely. However, if the damage seems extensive or if you’re unsure, it’s best to hire a professional roofing contractor. They have the expertise to identify problems that may not be immediately obvious and can provide an accurate assessment.
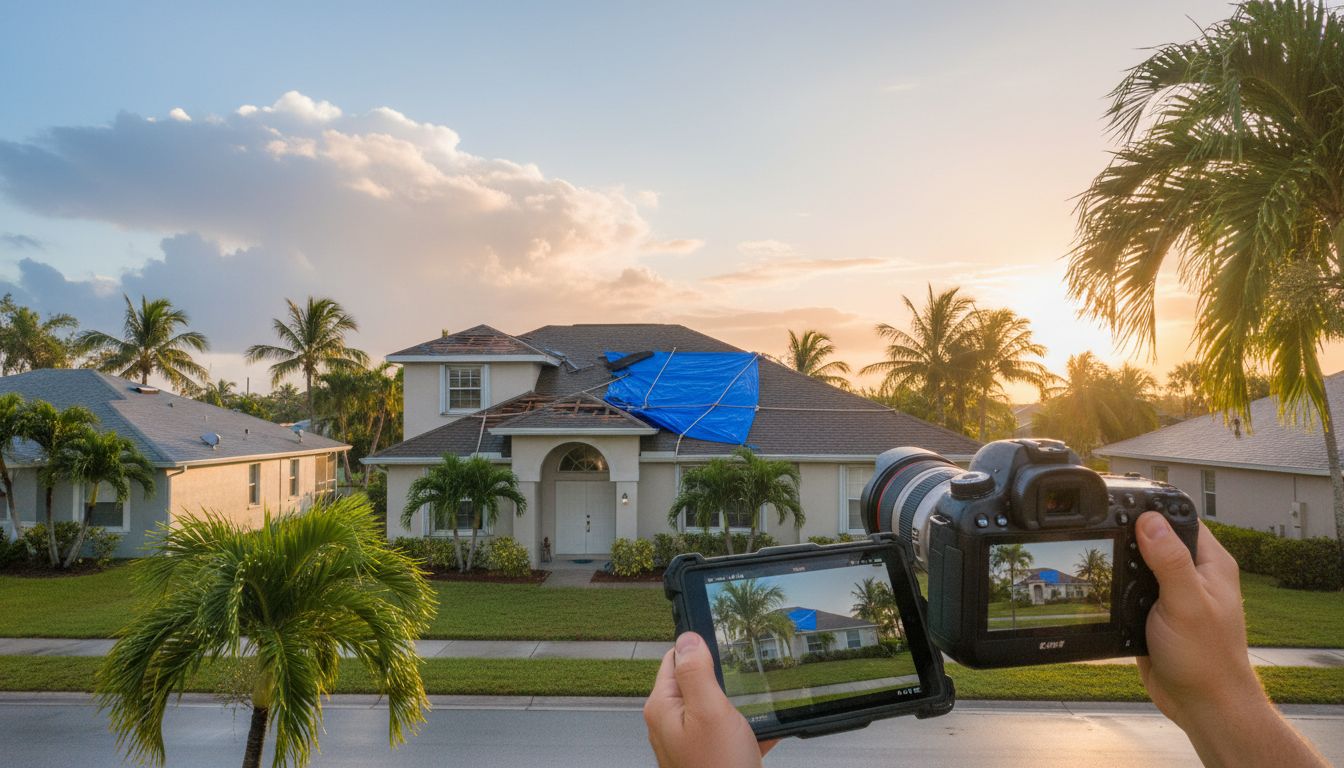
Once damage is identified, thorough documentation is essential. Take clear photos and videos of the affected areas, including close-ups and wide shots to show the extent of the damage. Keep detailed notes about what you observe and when. This evidence will serve as critical support for your insurance claim and help ensure you receive fair compensation.
Immediate Actions to Protect Your Property
After discovering roof damage, it’s important to act quickly to prevent further issues. If there are leaks, cover the damaged areas with tarps to stop water from entering your home. This is not only a practical step but also one that most insurance policies require to mitigate additional damage. Failing to take these precautions could result in denied claims or reduced payouts.
In addition to temporary fixes, notify your insurance company as soon as possible. Many policies have specific deadlines for reporting damage, so prompt action is key. By addressing the problem early, you demonstrate responsibility and increase your chances of a smoother claims process.
Understanding Your Insurance Policy
Before filing a claim, take time to review your insurance policy carefully. Most policies cover damage caused by wind, hail, and storms, but there are often exclusions for issues like wear and tear or aging. Understanding terms like "actual cash value" (ACV) and "replacement cost value" (RCV) is also important. ACV reimburses you for the current value of your roof minus depreciation, while RCV covers the full cost of replacing it with new materials.
Knowing your policy inside and out helps set realistic expectations for what your insurer will pay. If anything is unclear, don’t hesitate to contact your agent for clarification. Being informed ensures you won’t face unpleasant surprises during the claims process.
Initiating The Claims Process
To start your claim, gather all necessary information, including the date of the storm, photos of the damage, and any repair estimates you’ve received. Contact your insurance company promptly and provide them with this documentation. Most insurers have deadlines for filing claims, so acting quickly is crucial. During this initial stage, ask questions to understand how the process works and what to expect moving forward.
Once your claim is submitted, schedule an inspection with the insurance adjuster. Be prepared to present your evidence and explain the extent of the damage. This step sets the tone for the rest of the process, so thorough preparation is vital to securing a favorable outcome.
Professional Inspections and Contractor Reports
A licensed roofing contractor can provide invaluable assistance during the claims process. Their detailed inspection will uncover hidden damage and produce an official report complete with repair estimates and supporting images. This documentation strengthens your case and gives your insurer a clear picture of the repairs needed.
Hiring a reputable contractor also ensures accuracy and professionalism. Choose someone with experience in handling insurance claims and a solid reputation in the community. Their expertise can make a significant difference in how smoothly your claim progresses.
Insurance Adjuster Inspections
When the insurance adjuster visits your property, they’ll evaluate the damage and determine the scope of coverage. It’s important to accompany them during the inspection to ensure all affected areas are noted. Point out any specific concerns and provide your documented evidence to support your claim.
To ensure fairness, stay engaged throughout the inspection process. If you disagree with the adjuster’s findings, politely discuss your perspective and request a second opinion if necessary. Remember, the goal is to reach an agreement that accurately reflects the damage and required repairs.
Tracking Claim Communications and Deadlines
Keeping track of all communications related to your claim is essential. Use a notebook or digital tool to log every interaction with your insurer, contractor, and adjuster. Note dates, names, and key details discussed during each conversation. This record will help you stay organized and hold parties accountable if disputes arise.
Additionally, adhere to all deadlines for submitting documents and following up on requests. Missing these timelines could jeopardize your claim. Regular communication and attention to detail demonstrate diligence and improve your chances of a successful resolution.
Disputes, Denials, and Negotiation Options
Unfortunately, some claims are denied or underpaid due to reasons like insufficient documentation or misunderstandings about policy terms. If this happens, don’t panic—there are options available. Start by reviewing your denial letter carefully to understand the reasoning behind the decision. From there, you can appeal the decision through mediation or appraisal processes.
For complex cases, consider hiring a public adjuster or legal advocate. These professionals specialize in negotiating with insurers and can help you navigate the appeals process. While it may involve additional costs, their expertise often leads to better outcomes and faster resolutions.
Receiving Payment and Starting Repairs
Once your claim is approved, payments are typically disbursed in two parts: an initial payment to cover immediate expenses and a final payment upon completion of repairs. To access funds, you may need to provide invoices or proof of work completed. Understanding these requirements ensures you receive timely payments without unnecessary delays.
When choosing a contractor, prioritize those who are licensed, insured, and experienced in working with insurance claims. Verify their credentials and read reviews to ensure quality workmanship. Starting repairs promptly not only restores your home but also prevents further damage from worsening conditions.
Submitting Final Paperwork and Closing Out The Claim
After repairs are finished, submit all final paperwork to your insurer, including invoices and receipts. Schedule a final inspection to confirm the work meets both policy requirements and local building codes. This step ensures your claim is officially closed and any remaining funds are released.
Taking care to complete this phase thoroughly avoids complications later on. Double-check that all documents are accurate and submitted securely. Once everything is finalized, you can breathe easy knowing your roof—and your finances—are back in good shape.
Common Issues and Mistakes to Avoid
Several common pitfalls can derail a roof damage insurance claim. Missing documentation, failing to meet deadlines, and misunderstanding policy exclusions are frequent mistakes homeowners make. To avoid these issues, maintain meticulous records, stay proactive, and seek clarification whenever needed.
Another major mistake is hiring unlicensed contractors who may cut corners or overcharge. Always verify credentials and get multiple quotes before committing to anyone. By avoiding these errors, you’ll significantly increase your chances of a smooth and successful claims process.
Frequently Asked Questions
-
How soon do I need to file a roof damage claim after a storm?
Most homeowners' policies in Southwest Florida require claims to be filed within a specific timeframe, often ranging from 30 to 90 days after the storm. Filing promptly ensures you don’t miss deadlines and allows your insurer to investigate while evidence is still fresh.
-
What documentation is required for a roof damage claim?
You’ll need photos and videos of the damage, a contractor’s inspection report, repair estimates, the date of the storm, and completed claim forms. Providing comprehensive documentation strengthens your case and expedites the process.
-
Will insurance cover roof damage from wear and tear?
No, standard policies exclude damage caused by normal aging or deterioration. Coverage applies only to sudden events like storms or impacts. Regular maintenance can help extend your roof’s lifespan and reduce the risk of uncovered claims.
-
Can I choose any contractor to repair my roof after a claim is approved?
While you have the freedom to choose, it’s wise to select a licensed, insured contractor familiar with insurance claims. Some insurers recommend approved networks, and all repairs must comply with Florida building codes and policy requirements.
-
What if my claim is denied or the settlement is too low?
If your claim is denied or undervalued, you can appeal through mediation or appraisal processes. Hiring a public adjuster or legal advocate may also be beneficial. These professionals specialize in maximizing settlements and resolving disputes effectively.
Conclusion
Filing a roof damage insurance claim in Southwest Florida doesn’t have to be overwhelming. By taking a proactive and organized approach, you can navigate the process with confidence. From documenting damage to understanding your policy and working with professionals, each step plays a vital role in achieving a successful outcome.
Begin assessing your roof today and review your insurance policy to familiarize yourself with its terms. Document any suspected damage and reach out to trusted contractors or adjusters if needed. Remember, Florida law protects your rights as a homeowner, and resources are available to assist you. With detailed documentation, prompt action, and a clear understanding of your policy, you’re well-equipped to maximize your claim’s success.